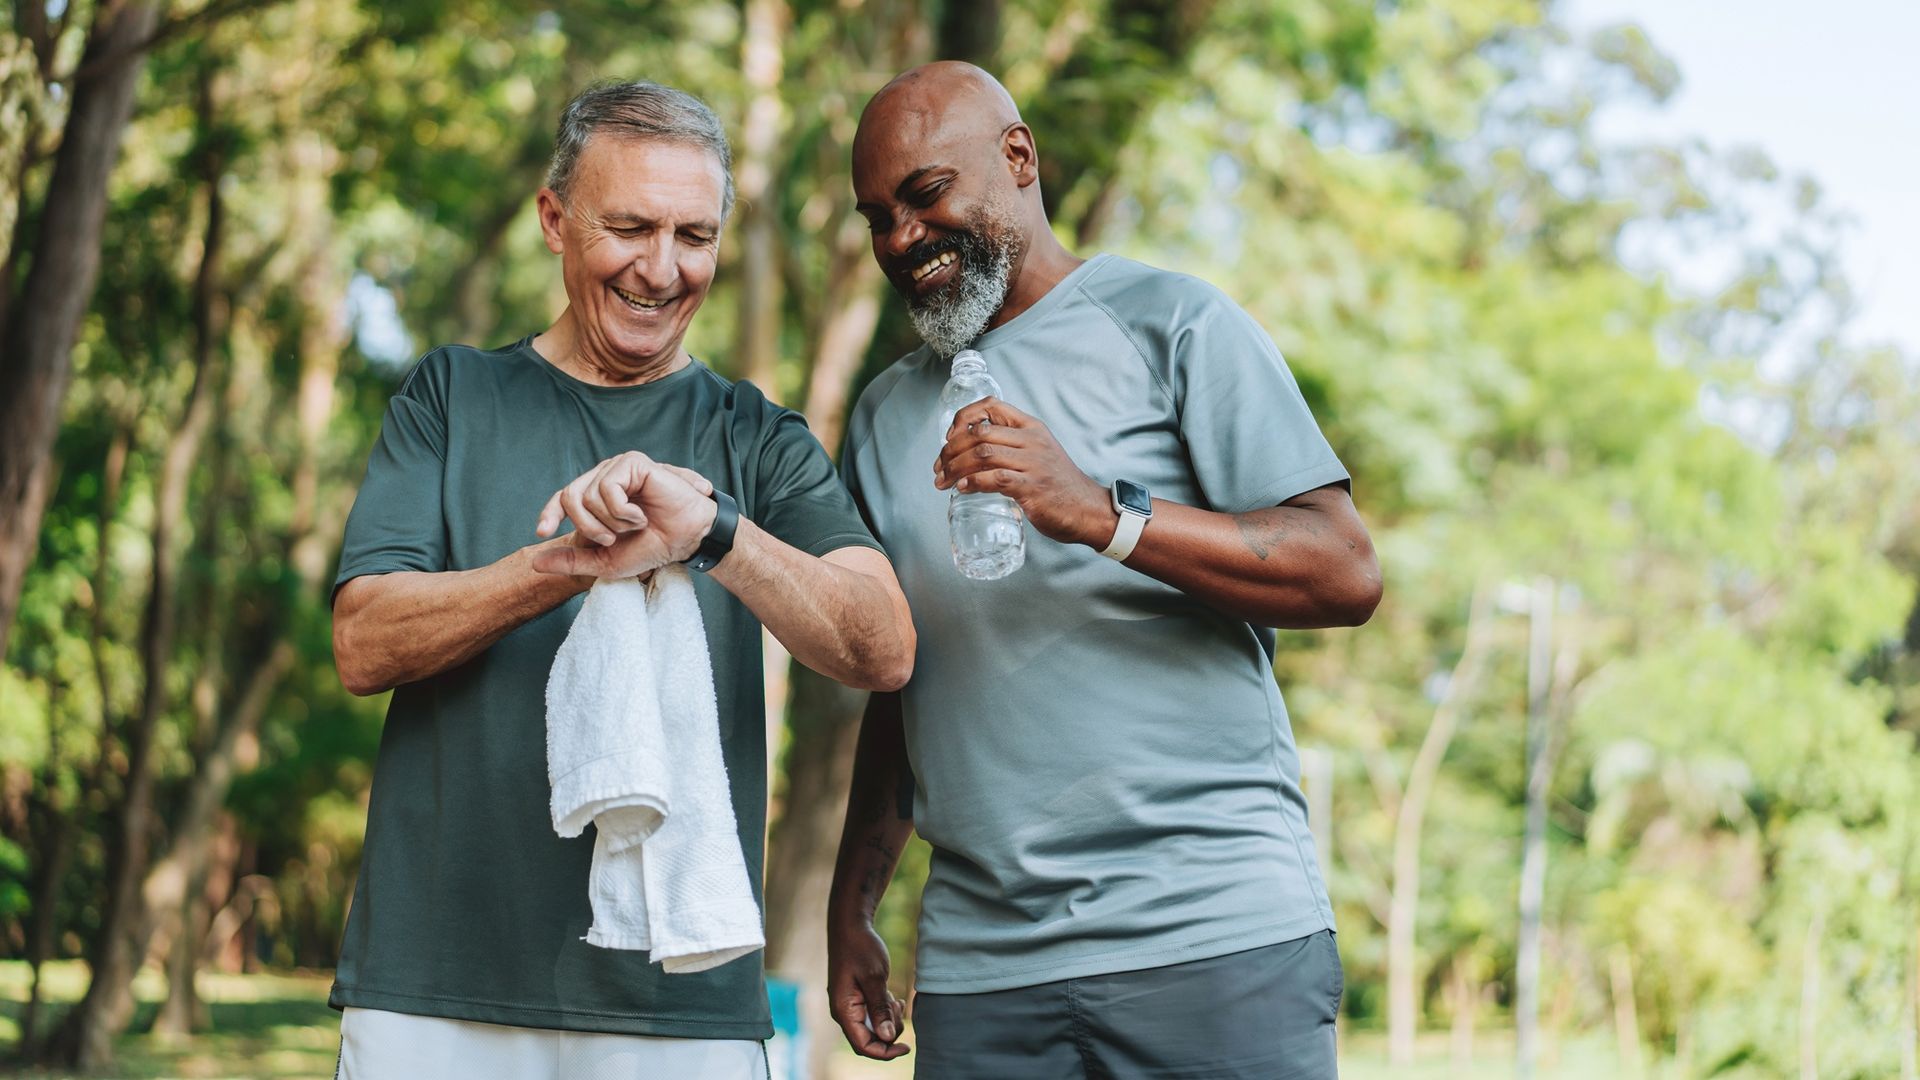
# Why Exercise Is Your Best Retirement Investment
A growing body of research shows that staying physically active in midlife and beyond delivers measurable financial returns in retirement. Regular exercise can delay the onset of long-term care needs by approximately two years, a benefit that translates to tens of thousands of dollars in avoided medical expenses and care costs.
The math works in your favor. Long-term care in the United States costs between $4,500 and $8,000 per month for assisted living and $8,000 to $15,000 monthly for nursing home care, according to Genworth's 2023 Cost of Care Survey. A two-year deferral means avoiding 24 months of these bills. For someone facing nursing home costs of $10,000 per month, that two-year extension eliminates roughly $240,000 in expenses.
This return on investment beats most retirement strategies. A diversified stock portfolio averaging 7 percent annual returns cannot match the certainty and magnitude of healthcare cost avoidance that physical fitness provides. The benefit remains tax-free and requires no market timing or investment sophistication.
The mechanism behind this benefit operates through multiple pathways. Regular exercise strengthens muscles and bone density, reducing fall risk and fracture rates that commonly trigger long-term care admissions. Physical activity maintains cardiovascular health, lowering rates of stroke and heart disease that precipitate nursing home placement. Exercise also preserves cognitive function and mobility, allowing people to remain independent in their homes longer.
Walking, swimming, resistance training, and flexibility work all contribute to this outcome. You need not become an athlete. Studies show that 150 minutes of moderate aerobic activity weekly, combined with twice-weekly strength training, produces the documented benefits. This aligns with guidelines from the American Heart Association and the CDC.
The retirement planning implications are substantial. Many people purchase long-term care insurance, which costs $1,500 to $3,000 annually for individuals starting policies in their 50s. A regular exercise regimen costs far less. A gym membership runs $20 to $100 monthly. Walking requires zero dollars. Swimming at a public facility typically costs $5 to $15 per visit.
Financial advisors increasingly recognize this reality. Long-term care expenses represent one of the largest unbudgeted retirement risks for households with assets between $250,000 and $2 million. These households often skip long-term care insurance due to cost but face significant exposure to care expenses. Exercise provides a low-cost risk reduction tool that works alongside insurance, not as a replacement.
Starting early amplifies benefits. A 50-year-old who establishes a consistent exercise routine builds physical reserves that compound over decades. A 70-year-old beginning exercise derives immediate gains but cannot recover lost decades of muscle and bone density.
The retirement accounts in your portfolio deserve attention, but your body deserves more. Every workout today represents a direct investment in staying out of nursing homes tomorrow. This inverse relationship between physical fitness and long-term care dependency creates a financial return that rivals any mutual fund. Your best retirement asset is the one you build through consistent movement, not one you buy through a brokerage account.