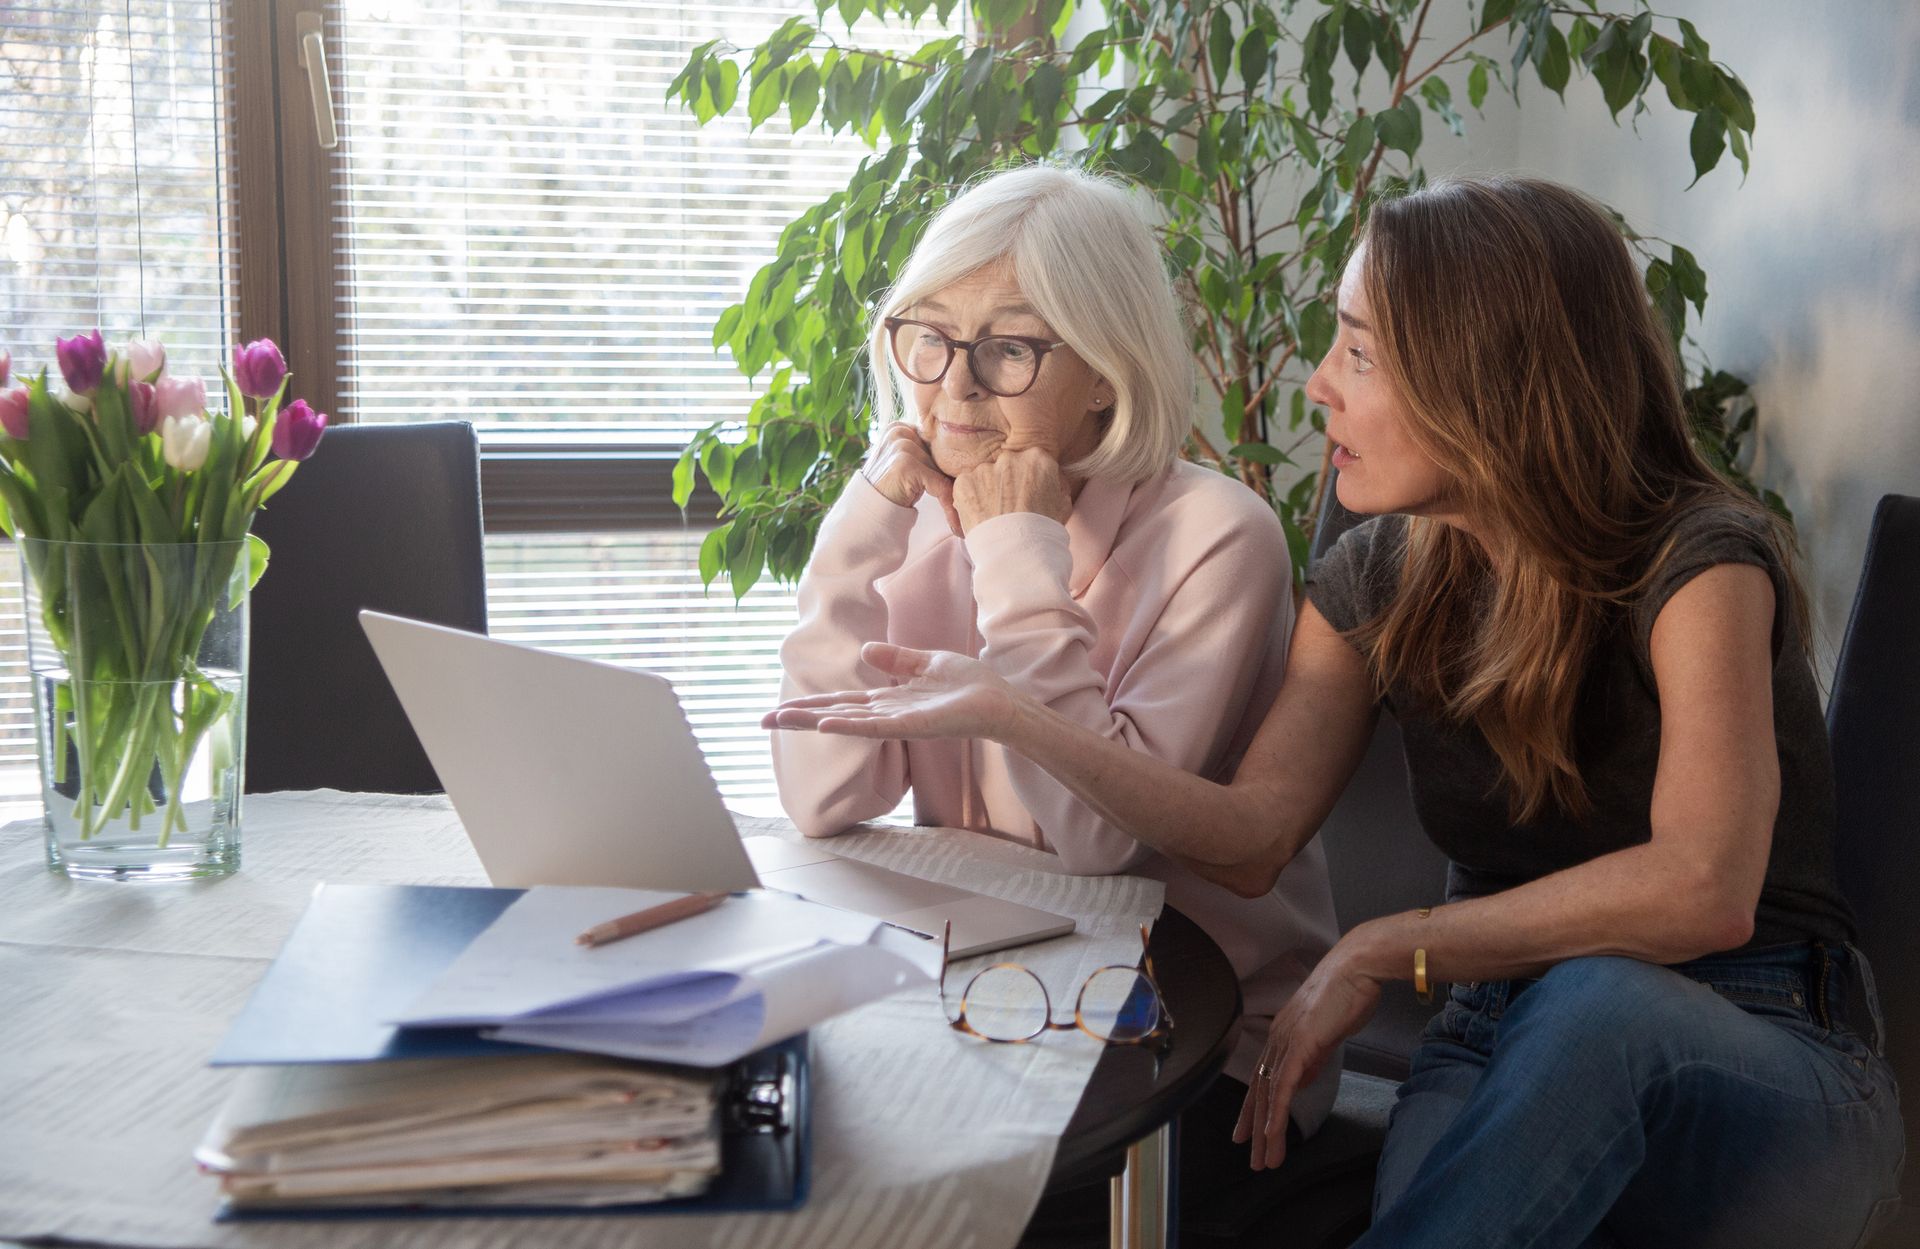
# How to Talk With Your Aging Parents About Money Without the Awkwardness
Most adult children avoid the financial conversation with aging parents. The discomfort runs deep. You worry about seeming greedy. Your parents worry about losing independence. Both sides fear what comes next. Yet avoiding these talks often leads to crisis: a parent dies without a will, medical bills pile up uncovered, or someone discovers hidden debt months too late.
Starting the conversation early beats scrambling later. Here's how to do it without damage.
**Pick the Right Moment**
Timing matters. Don't ambush your parents during a family dinner or holiday. Instead, ask for a private meeting. Choose a calm moment when everyone is relaxed and nobody feels rushed. Frame it as planning, not interrogation. Say something like, "I'd like to understand your financial situation so I can help if you need me." This positions you as a helper, not an inspector.
**Start With Questions, Not Statements**
Ask open-ended questions first. "What does your retirement look like?" or "Do you have a will?" beats lecturing. Let them lead. You'll learn their comfort level with money talk and what information they actually want to share. Some parents volunteer everything freely. Others need time to build trust.
**Know What You Need to Know**
Before the conversation, decide what matters. You need to know: where they bank, what passwords or documents you might need, whether they have a will or power of attorney, what insurance they carry, where they invested their money, and who their accountant or financial advisor is. You also need contact information for their lawyer and any healthcare providers making decisions about long-term care.
**Bring in a Professional If Needed**
Sometimes parents hear bad news better from a stranger. A financial advisor, accountant, or estate attorney can validate your concerns without the emotional charge. Your parents might listen to a professional about consolidating accounts or reviewing beneficiaries when they'd dismiss the same advice from you.
**Document Everything**
Once your parents share information, write it down. Create a file with account numbers, passwords (stored securely), insurance policies, and contact information for all advisors. Keep a copy in your home and another with your estate documents. Many parents appreciate this. It removes the burden of remembering where everything lives.
**Respect Their Autonomy**
Remember your parents still control their money. Your job is to understand their situation and help manage it if they ask. Pushing too hard backfires. Let them make their own choices even if you disagree. The goal is information and trust, not control.
**Set a Timeline**
These conversations work best as an ongoing process, not a one-time event. Plan annual check-ins. Review changes in their situation, tax law updates, or new accounts they've opened. Regular contact normalizes the discussion and catches problems early.
Starting now, even if your parents are in their 60s, prevents panic later. The longer you wait, the harder the conversation becomes. Your parents might develop cognitive decline, or they might pass suddenly. Either way, you'll wish you'd asked sooner.