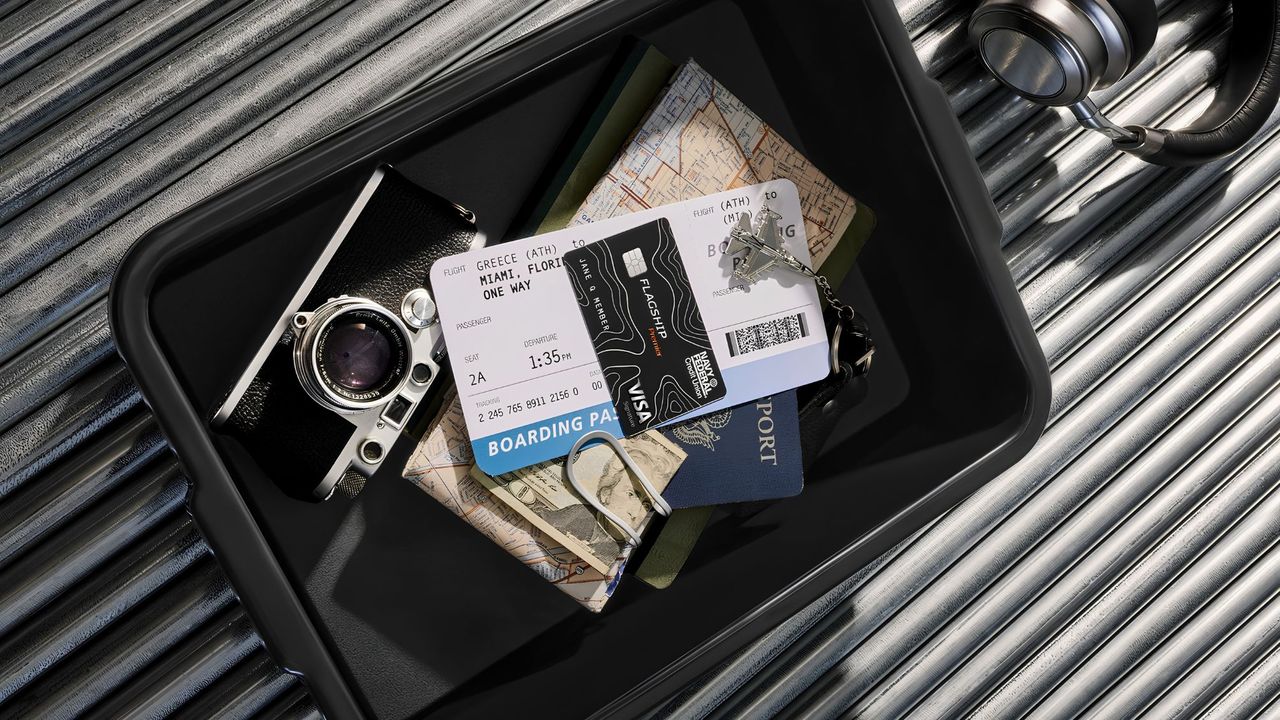
# Navy Federal Flagship Premier Visa Signature Card Positions Itself as Travel-Focused Competitor
Navy Federal Credit Union launched its Flagship Premier Visa Signature card into an increasingly crowded travel rewards market. The card targets active travelers seeking straightforward benefits without the complexity of category-based earning schemes.
The Flagship Premier offers a streamlined rewards approach. Details on earning rates remain limited in the initial announcement, but Navy Federal positions this card around Visa Signature benefits that appeal directly to frequent flyers and hotel guests. These benefits typically include travel protections, concierge services, and airport lounge access across the Visa Signature network.
Visa Signature cards generally deliver value through travel-specific perks rather than rotating categories. This differs sharply from premium cards like the Chase Sapphire Reserve or American Express Platinum, which charge substantial annual fees ($550 and $695 respectively) but pile on credits and elite benefits. The Navy Federal approach appeals to cardholders who want travel protection without annual fees that climb past $200.
Navy Federal operates as a credit union with membership requirements. Access depends on eligibility criteria, which typically include military service, family connections to service members, or Department of Defense employment. This membership gate limits the card's audience compared to bank-issued competitors. However, for eligible members, Navy Federal consistently offers lower annual fees and more flexible approval standards than traditional banks.
The travel card landscape has shifted considerably. Bank of America's premium travel card recently underwent changes. Chase has multiple tiers from the entry-level Freedom Unlimited to the luxury Sapphire Reserve. American Express focuses heavily on business and premium segments. Capital One remains active in the travel space with the Venture card.
For ordinary cardholders, a simple rewards structure beats complexity. Credit card companies increasingly pile on quarterly categories, rotating bonuses, and activation requirements that many users forget. Navy Federal's reported simplicity could resonate with travelers who value clarity over optimization.
The card's value depends entirely on annual fee structure and rewards earning rates. A no-fee card with 1.5X points on all travel purchases could outperform a $95 card offering 2X points on categories. A $0 annual fee makes sense for casual travelers. A $95 to $150 fee requires strong benefits to break even.
Visa Signature protections typically include trip cancellation insurance, baggage delay reimbursement, and emergency medical and dental coverage abroad. Airport lounge access through programs like Priority Pass adds practical value for road warriors.
Navy Federal membership eligibility creates both opportunity and limitation. Current members may see this card as a natural upgrade from standard Navy Federal offerings. Non-members interested in the card need to confirm membership eligibility first, as applying for an ineligible account wastes time and creates a hard inquiry on credit reports.
Potential cardholders should compare this offering directly against Chase Freedom Flex, Capital One Venture, and regional options before deciding. The winning choice depends on annual fee structure, actual rewards rates, and which travel protections matter most to individual spending patterns. Navy Federal's entry into premium travel cards signals continued innovation in credit union offerings.